What the FAIR Plan's 29% rate hike costs East Bay hill towns
The California FAIR Plan's average 29.1 percent increase is now in effect at renewal. We ran the plan's own ZIP data to show what it adds in Orinda, Lafayette, Danville, Moraga and the Oakland hills.
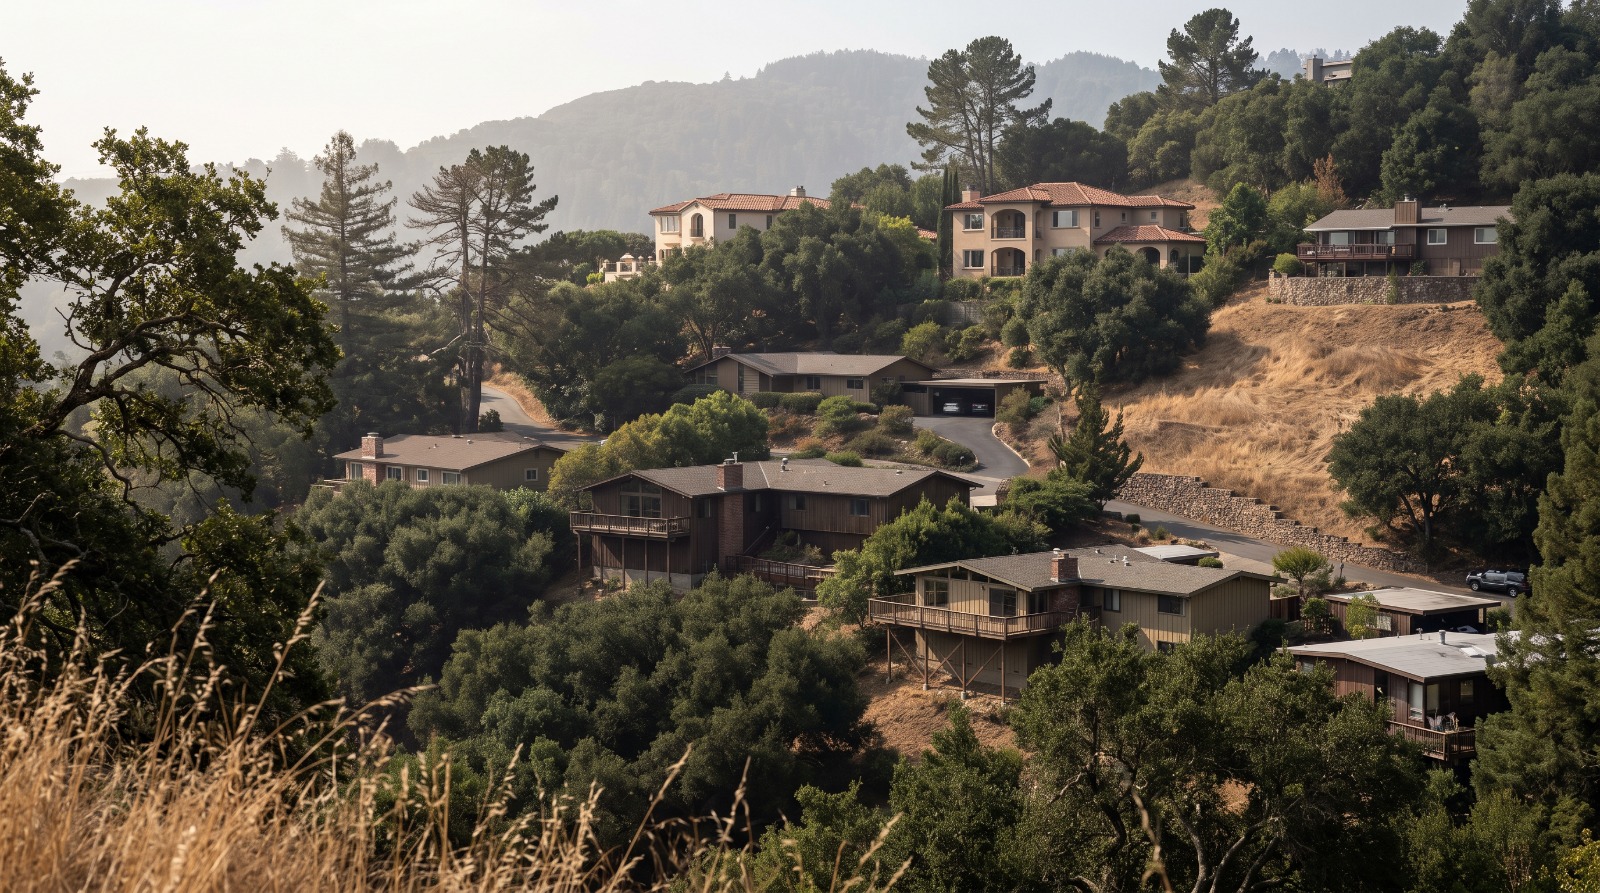
AI-rendered telephoto view of hillside homes among oaks in Orinda, California, in the East Bay hills Photo: Houseberry
In Orinda, the average California FAIR Plan homeowner policy carried about $5,026 in annual premium at the end of June. The plan's 29.1 percent average rate increase took effect October 15, 2026, and an increase that size on that bill is about $1,460 a year, or roughly $122 a month.
That is our math from the FAIR Plan's own ZIP code files, and Orinda is not unusual. Across the Oakland hills and the Lamorinda and Danville suburbs, the average policy runs $3,800 to $5,800 a year before the increase. Those are also places where very few homes used the FAIR Plan five years ago. In Orinda's 94563 ZIP code there were 157 residential FAIR Plan policies in September 2021. By June 30, 2026 there were 2,691.
Against Houseberry's Orinda data, where the typical home sold for about $2.0 million in September 2026, the increase is small next to the mortgage. It is still a new line in a budget that did not have one in 2021.
Who gets the bill first
The FAIR Plan is California's insurer of last resort, a pool every licensed property insurer in the state has to join. Its 665,862 homeowner policies carried about $1.8 billion in premium as of June 30. It covers fire and a short list of other perils, and homeowners usually pair it with a separate "difference in conditions" policy for theft, water damage and liability.
The rate change is not one number. The plan sets prices by location and wildfire risk, and its June 2026 policy file sorts every ZIP's policies into three risk tiers, from low to high. Half of Orinda's FAIR Plan homes sit in the high tier. In Rockridge's 94618, none do. That spread is why one homeowner's renewal can go down while a neighbor's in the canyon above goes up by a third.
California law generally requires an insurer to send the renewal offer at least 45 days before the policy expires. If yours renews in late November, the new price should be arriving now.
The surge in FAIR Plan homes is the story the rate increase lands on. Here is how residential policies grew from September 2021 to June 2026 in eight Bay Area hill ZIP codes, from the plan's published key statistics.
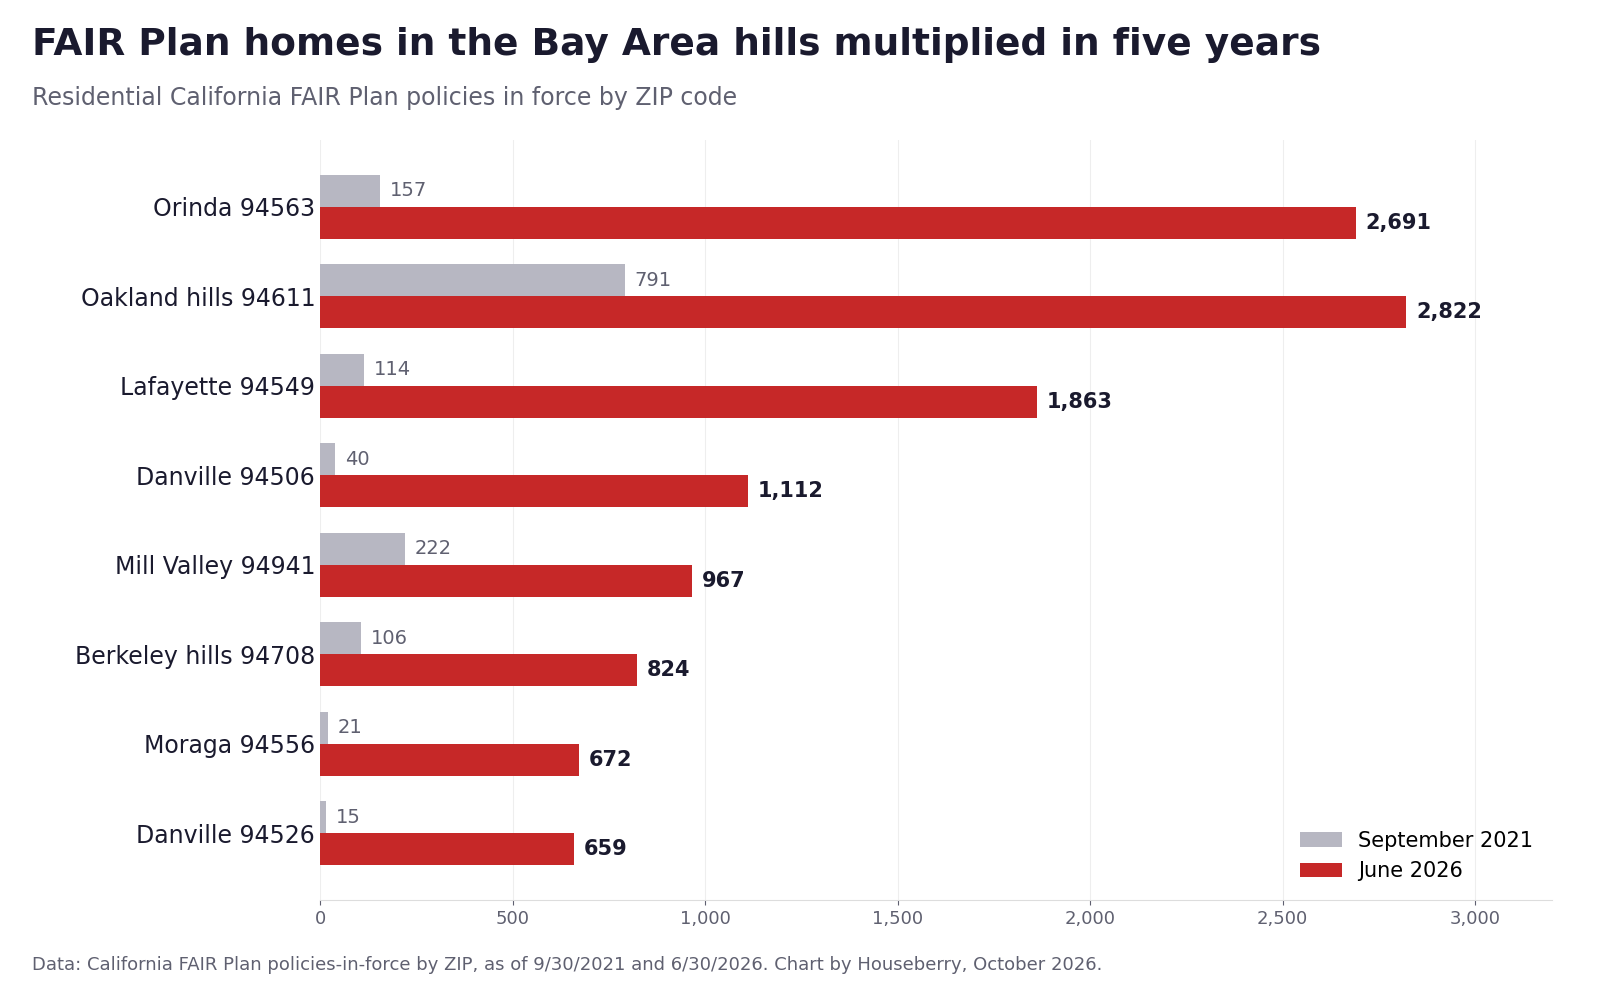
Danville's west side, 94526, grew from 15 policies to 659. Moraga went from 21 to 672. Those are not wildfire-country addresses in the way Paradise or Grizzly Flats are. Only 8 percent of the 94526 policies sit in the plan's high-risk tier. These are suburban ZIPs where many regular insurers stopped writing new policies, and the FAIR Plan was what remained.
What the increase costs, by ZIP
The table below divides each ZIP's total written premium by its policy count, which gives the average FAIR Plan bill there as of June 30, 2026. The last two columns apply the statewide 29.1 percent average. Your own change will differ, so treat these as a yardstick.
| ZIP and place | FAIR Plan homes, June 2026 | Average premium | At +29.1% | Typical home, Sep 2026 |
|---|---|---|---|---|
| 94506 Danville (east) | 1,112 | $5,803 | $7,492 | $2.10M |
| 94563 Orinda | 2,691 | $5,026 | $6,488 | $2.00M |
| 94611 Oakland hills | 2,822 | $5,020 | $6,481 | $1.60M |
| 94549 Lafayette | 1,863 | $4,930 | $6,365 | $2.12M |
| 94526 Danville (west) | 659 | $4,835 | $6,242 | $2.10M |
| 94556 Moraga | 672 | $3,794 | $4,898 | $1.83M |
| 94618 Rockridge | 273 | $2,894 | $3,736 | $2.26M |
Home prices are from Houseberry's September 2026 price histories for Lafayette, Danville, Moraga, Orinda, and the Montclair and Rockridge neighborhood pages in Oakland.
Two findings jump out. The Oakland hills ZIP has the most FAIR Plan homes on this list and the cheapest typical house, about $1.6 million in Montclair. And the gap between the top and bottom rows is about $3,750 a year in projected premium, between two ZIP codes about 20 miles apart.
Our view
We think the increase is the honest price, and the fight worth having is over who else will write these homes. The FAIR Plan's last increase, 15.7 percent in 2023, came before the Los Angeles fires and the $1 billion assessment that followed them in February 2025. A last-resort pool that underprices risk ends up passing the bill to every insured homeowner in the state. Somebody pays either way.
The fix that actually lowers a Lafayette homeowner's bill is a regular insurer coming back. State rules adopted under Commissioner Ricardo Lara's Sustainable Insurance Strategy let insurers use catastrophe models in exchange for writing more policies in high-risk areas, and CalMatters reported in September that the state has not yet said how many new policies that has produced. The FAIR Plan's clearinghouse, which offers its customers to private insurers, has moved only about 750 homes back to the regular market so far, according to testimony at a March 2026 Assembly hearing.
That is the question on the November 3 ballot too. Jane Kim and State Senator Ben Allen are running to replace Lara.
Read the renewal offer when it arrives and compare it with this year's bill line by line. Ask your broker whether a regular insurer such as Mercury or Farmers, both of which made new-policy commitments under the Sustainable Insurance Strategy, will now write your house, especially if you have done the home hardening work that earns the plan's wildfire discount. Check that your difference in conditions policy renews on the same cycle.
We covered how the other big insurers' rates are moving in our look at Farmers' 1.5 percent change. And if you are shopping in the hills, check each town's scores on Houseberry's East Bay ranking before you budget, because in Orinda an insurance line that barely existed in 2021 now runs about $540 a month at the new average.
Sources
- California FAIR Plan: key statistics and ZIP code data, June 30, 2026
- KQED: California FAIR Plan announces 29.1% rate hike for homeowners this fall
- KRCR: California FAIR Plan to raise homeowners insurance rates about 29%, May 22, 2026
- California Department of Insurance: FAIR Plan assessment, February 11, 2025
- CalMatters: Insurers' new policy commitments, September 23, 2026
- KPBS and CalMatters: The insurance commissioner candidates, October 9, 2026
The Houseberry Research Team is Houseberry's reporting team: Bay Area real estate analysts, data specialists and longtime local market watchers. Every day we check the public record: building permits, city council and planning agendas, county recorder filings, state housing bills, police incident data and school results. Then we tie each story to what it means for specific neighborhoods, using Houseberry's own neighborhood data on prices, appreciation, safety, schools and amenities. Questions or corrections: Contact us.
Map of East Bay Neighborhoods
Loading map...
View Full Map
Top Neighborhoods in East Bay, CA


All information provided on this website including but not limited to - school ratings, safety, amenities, user opinions, and property data - is for general informational purposes only. We do not guarantee its reliability, accuracy, or completeness. Users should independently verify information and consult appropriate professionals as needed. By using this website, you agree Houseberry is not responsible for actions, decisions, or consequences arising from reliance on the information provided
houseberry.com - CA DRE# 01847391
 Bay East ©2025. CCAR ©2025. bridgeMLS ©2025. Information Deemed Reliable But Not Guaranteed. This information is being provided by the Bay East MLS, or CCAR MLS, or bridgeMLS. The listings presented here may or may not be listed by the Broker/Agent operating this website. This information is intended for the personal use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Data last updated at October 18, 2026 12:00 AM